

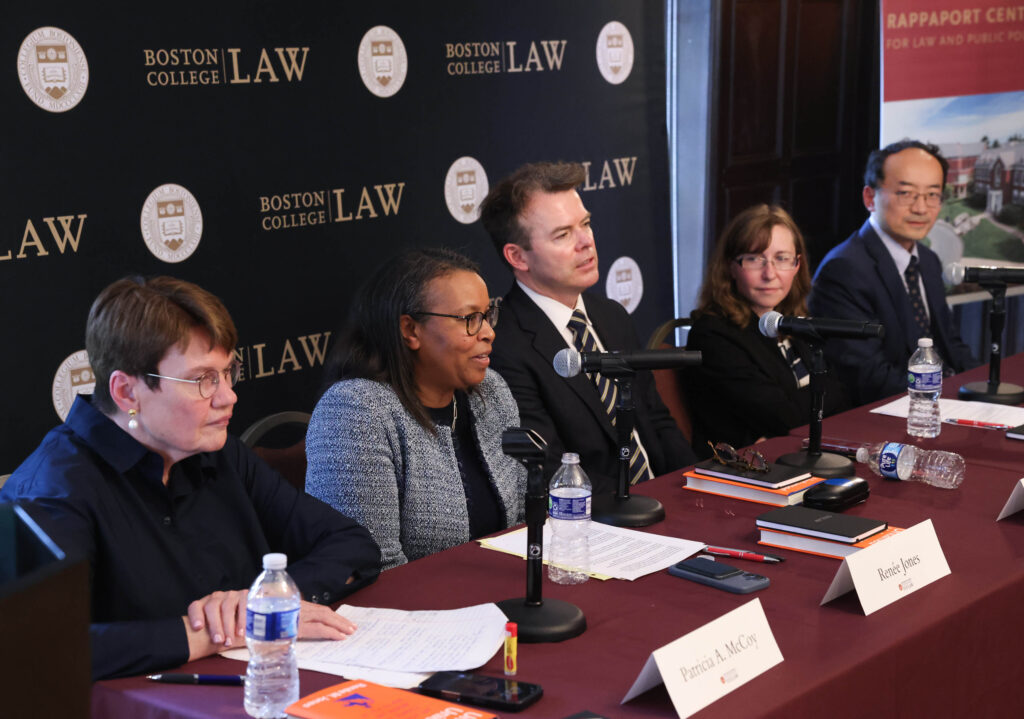
A company can be worth billions of dollars, employ thousands of people, and attract some of the world’s largest investors, yet still operate without making the same disclosures expected of a public company. At a recent Boston College Law School book talk, that tension framed a wide-ranging discussion of Professor Renée M. Jones’s new book, Untamed Unicorns: Why Startup Finance Is Broken and How to Fix It, and the legal and financial changes that have reshaped the startup economy.
Jones was joined by William Birdthistle of the University of Chicago Law School, Nadya Malenko of Boston College’s Carroll School of Management, Haoxiang Zhu of MIT Sloan School of Management, and moderator Patricia McCoy of BC Law. Each approached the rise of the modern unicorn from a different direction. Malenko examined the shift toward founder-controlled governance and dual-class shares. Zhu focused on the venture-capital model and what companies escape when they delay going public. Birdthistle considered the role of public markets and the regulatory choices that have helped redraw the boundary between public and private companies.
Running through the conversation was a larger question: What happens when companies can grow up without going public? For an earlier generation of startups, an IPO was not simply a fundraising event. It brought scrutiny and disclosure, gave investors and employees a way to cash out, and pushed companies toward more professional management.
Today, deep pools of private capital and new avenues for liquidity have weakened many of those pressures. A successful startup can raise enormous sums and remain private far longer, even as its reach begins to resemble that of a public company. Jones argues that this transformation did not happen by accident. Her book traces a series of changes to securities law that helped private markets expand, including the JOBS Act of 2012, which raised the shareholder threshold that can trigger public reporting requirements from 500 to 2,000 and excluded employee-held shares from the count. The panel followed those changes through their consequences, from increasingly powerful founders and diminished investor oversight to employees asked to evaluate stock compensation with limited information.
In the following Q&A, Jones brings an unique vantage point to those questions. A scholar of securities regulation, she also served as director of the SEC’s Division of Corporation Finance from 2021 to 2023. Following the book talk, she spoke with BC Law Magazine about Untamed Unicorns and how the startup financing system reached this point, what has been lost as companies remain private longer, and how regulation might catch up.
Q: Untamed Unicorns traces how startups that once would have entered the public markets can now grow to enormous size while remaining private. Has that shift changed what it means, in economic or regulatory terms, for a company to be “private”?
Jones: A private company is not required to make the periodic SEC disclosures required of a public reporting company. With a public company, we can see information about its finances, management, controlling shareholders, material risks, and legal problems. With a private company, that information generally is not publicly available.
Notably, the number of the large companies that operate outside that disclosure system has proliferated. For roughly 40 years, we have been deregulating the securities markets in ways that allowed private markets to expand. Because of these reforms, most notably a 1996 statute [the National Securities Markets Improvement Act] that lifted the cap on the size of private investment funds, private investment funds can raise much more money than they could in the past.
Historically, if a startup was growing rapidly and needed substantial amounts of capital, at some point it had to turn to the public markets for financing. There simply was not enough money available privately. As the laws changed, that constraint has largely disappeared. A startup can now raise enormous amounts of money without registering with the SEC and without making the disclosures required of a public company. So, we have companies that are private as a matter of securities law but that have the valuation, workforce, customer base, and economic significance that we once associated only with public companies.
Q: One of the tensions you identify is that venture capitalists have more money to invest but, in some cases, less control over the founders receiving it. What changed in the relationship between founders and their investors?
Jones: There is now much more money competing for a relatively small number of desirable investments. Venture capitalists are competing with one another, but they are also competing with mutual funds, corporate venture funds, sovereign wealth funds, and other investors.
That competition changed the bargaining relationship. We moved toward what is often called a founder-friendly financing model.
Traditional venture-capital financing included a number of protections for investors. Venture capitalists took seats on the board. They would receive redemption rights, which might allow them after a period of years to say, essentially, we are done and want our money out. They would receive registration rights that gave them leverage to push the company toward an IPO. As successive financing rounds diluted the founder’s ownership, control would gradually move toward the investors who were supplying more of the company’s capital.
We see these kinds of protective provisions less frequently now. Now, founders often receive “supervoting” shares, a specialized class of corporate stock that gives holders disproportionately more voting power per share compared to the single vote per share granted to regular common stock, carrying 10 votes per share. That means the founder can retain voting control even though outside investors have supplied most of the money and own most of the company’s economic interest. Because voting control determines who sits on the board, investors and directors may have limited ability to remove the founder or force a change in strategy.
WeWork illustrates what can happen under that structure. WeWork was in the business of taking long-term leases on office space and renting out that space on a short-term basis. Yet, it invested in a wave-pool company because its founder, Adam Neumann, liked to surf. WeWork also created a school after Neumann and his wife became dissatisfied with the schools available to their children. Those were uses of corporate resources far removed from the company’s core business. The issue is not simply that a founder made an unusual decision; it is that investors had financed a governance structure that made it difficult for them to stop those decisions.
Q: Theranos, WeWork, Uber, and FTX loom large in the book, and each became closely identified with an individual founder. Does the attention paid to those personalities make it harder to see the institutional failures that allowed their behavior to continue?
Jones: For the public, I think it can. They are fascinating stories because the personalities are so unusual. We have The Dropout about Theranos, dramatizations of WeWork and Uber, and documentaries about these companies. Those accounts can be useful because they show people what happened inside the firms. But they can also distract from why the founders had that much control in the first place.
My interest is in the legal and financial structures underneath those stories. Why would sophisticated investors put enormous amounts of money into a company while accepting limited information or limited control? Why would they agree to supervoting shares that made the founder difficult to remove? Why did a financing system that historically gave venture capitalists significant monitoring rights begin producing companies in which those rights were weaker?
The legal changes I trace allowed founders to raise much larger amounts of private capital. Competition among investors then strengthened the founder’s bargaining position. A founder who was a very effective storyteller or marketer could raise enormous sums without necessarily having a sound business plan.
I began writing about this in 2017, when Uber was facing a backlash over its workplace culture and Theranos was already unraveling. I wrote a law review article titled, “The Unicorn Governance Trap.” My concern was that venture capitalists were giving founders voting control and other protections that made it difficult for investors to remove them when their performance or conduct became a problem. Then we saw WeWork abandon its attempted IPO in 2019, and in 2022 we saw FTX implode. Those companies had different businesses and different founders, but their failures followed a similar pattern. Analyzing the common governance arrangements can be more instructive for understanding this pattern than focusing on the personalities alone.
Q: You describe the IPO as a governance transition as well as a financing event. What did preparing to go public force a company to do that it can now postpone?
Jones: There used to be a fairly predictable venture-capital timeline. Investors would put money into a company during its early years and then look for an exit over roughly a 10-year period. If the company succeeded, it would be sold or go public within that 10-year timeframe, and an IPO was usually the preferred outcome. There were several factors that kept everybody moving in that direction: the company needed additional capital, venture investors wanted an exit, employees had stock and wanted to sell it, founders had accumulated sweat equity and wanted liquidity.
The “500-shareholder rule” [Section 12(g) of the Securities Exchange Act] also mattered. Before the Jumpstart Our Business Startups Act (JOBS Act) of 2012, any company with 500 or more shareholders faced mandatory public reporting requirements. Startups commonly issued options to employees, and as employees exercised those options, the company moved closer to that threshold. The 500-shareholder rule helped push companies such as Microsoft, Google, and Facebook toward public status. As a result, companies adjusted their structure as they approached that point. They brought in executives with experience managing public companies. For example, Google brought in Eric Schmidt. Facebook brought in Sheryl Sandberg. They hired reputable accountants and independent directors. The company needed to show it had the financial controls, management expertise, and a structure that could withstand scrutiny from public investors.
Today, a successful startup may not need venture capital for its later financing rounds. It can turn instead to a large technology company, a mutual fund, or other institutional investors capable of investing billions of dollars at once. Those nontraditional investors may not want board seats. They may not want to participate in management. At the same time, the parties who once needed an IPO to obtain liquidity can now get liquidity in private trading markets. Early investors can sell portions of their holdings in late-stage financing rounds. Founders can sell their stock or borrow large sums against it.
Consequently, many of the incentives that once pushed everybody toward an IPO have disappeared at the same time. As a result, the management shifts that were once routine under the old IPO timeline can be postponed.
Q: Employees are especially complicated in your account because they are both workers and investors. What does an employee actually know when a startup offers stock as part of a compensation package?
Jones: Potentially very little. Startups historically used stock compensation for two reasons. They were cash-poor, so paying part of compensation in equity preserved cash. Equity also tied the employee to the company because the employee’s rights typically vested over time. If the company succeeded and its value increased, staying longer could make the employee’s equity more valuable.
The SEC adopted Rule 701 to allow private companies to issue securities to employees without registering those offerings. The exemption makes sense in some respects because companies need a practical way to compensate employees with stock. But the disclosure requirements under Rule 701 are limited. An employee might receive a job offer that says, “We will pay you this salary, plus options to purchase this number of shares.” But the employee may not know the value of one share. They may not know how many shares are outstanding, so they cannot determine what percentage of the company their options represent. They may not have financial statements that would allow them to evaluate the company and its prospects.
Imagine comparing two job offers: one company offers more cash where another offers less cash plus equity. If you cannot value the equity, you cannot make an informed comparison. The problem continues after the employee joins the company. If you are considering exercising your options, you need to know whether paying the exercise price makes sense. If you leave the company and have a limited period in which to exercise options after your employment ends, the decision can involve a substantial amount of your own money.
Even where companies provide information, access can be inadequate. Some companies make documents available in an online data room but prevent employees from printing them. Others have required employees to review information in a physical room during limited hours. I think employees should receive enough information to evaluate their equity and should be able to retain and review that information. Companies can require confidentiality. However, confidentiality and meaningful disclosure are not mutually exclusive.
Q: The traditional justification for lighter regulation of private markets is that sophisticated investors can protect themselves. Why does that assumption break down in the market you describe?
Jones: Being “sophisticated” does not guarantee that you can always obtain sufficient information to make sound decisions. An institutional investor can have lawyers, accountants, financial analysts, and substantial experience evaluating companies. However, if the founder refuses to provide information and there are other investors willing to finance the company without that information, the investor has a choice: accept the founder’s terms or lose the investment.
FTX provides a concrete example. At Sam Bankman-Fried’s trial, one investor testified about his efforts to conduct due diligence. Bankman-Fried resisted and accused the investor of leaking information, and the investor backed down. That is a bargaining-power problem, not an intelligence problem. The investor may know exactly what due diligence it should perform. But if insisting on that due diligence means being excluded from a highly sought-after financing round, competitive pressure can cause even sophisticated institutions to accept terms they ordinarily would not. That is why I do not think the assertion that “these are sophisticated investors” ends the regulatory inquiry.
Q: The JOBS Act was promoted in part as a way to make going public easier. Yet you argue that one of its changes helped companies avoid going public. What happened?
Jones: As I mentioned, the JOBS Act was enacted in 2012. Part of the goal was to create an “on-ramp” to make an IPO easier for “emerging growth companies.” The idea was that reducing some of the burdens associated with becoming public would increase the number of IPOs.
But the JOBS Act simultaneously changed one of the rules that had pushed successful startups toward public status. As I mentioned, the former 500 shareholder threshold for mandatory SEC registration was increased to 2,000, excluding shares held by a startup’s employees.
So, one part of the statute was supposed to make the route into the public markets easier and increase IPOs, while another provision of the same statute essentially made entering the public markets optional.
Q: You were developing these arguments as a scholar and then served as director of the SEC’s Division of Corporation Finance from 2021 to 2023. What did you understand differently after seeing the regulatory process from inside the agency?
Jones: Working at the SEC gave me a more comprehensive perspective on the rulemaking process. As an academic, you can identify a problem and propose what you think is the best solution to the problem. Inside the SEC, you come to appreciate many additional considerations. You see questions about statutory authority. You benefit from the input of career staff and their years of experience and expertise. You read public comments, hear industry arguments, assess implementation challenges, and better appreciate the amount of work required to translate a policy idea into a rule that can work in practice.
That experience helped me when I was writing the reform proposals for my book. I went back and looked at the history of why certain rules were adopted, what policymakers hoped those rules would accomplish, what warnings or objections were raised at the time, and then what happened afterward. This research made me more attentive to exactly which rules need to change, whether the SEC has the authority to change them, and what kind of information and data would help to support that change.
Q: “Unicorn” originally described something exceptionally rare. After tracing how these companies became common, is it still the right term?
Jones: I sometimes think even “startup” is the wrong term. If a company has existed for 15 or 20 years and is valued at tens or hundreds of billions of dollars, in what meaningful sense is it still a startup?
The word “unicorn” also became aspirational. Founders want to reach a billion-dollar valuation because the designation attracts attention. Once the company reaches that status, the founder may have greater bargaining power, including the ability to demand supervoting shares.
I use the term because people understand what it means. But the label should not distract us from what these companies actually are. We are talking about large enterprises that employ thousands of people, serve millions of customers, raise billions of dollars from investors, yet are able to remain outside the disclosure system that applies to public companies.
Photograph by Reba Saldanha